
Research article · 2024 · Full text
International Journal of Agriculture Extension and Social DevelopmentStudy on credit utilization pattern and repayment behaviour of agriculture loan borrowers of lead bank
Volume 7(5) · Pages 96–98 · DOI: 10.33545/26180723.2024.v7.i5b.600 ↗
Research areasMicrofinance and Financial Inclusion
Abstract
Author-writtenCredit is a valuable financial resource enabling individuals to acquire necessary goods and services with the commitment to repay the borrowed amount within an agreed-upon timeframe. In the realm of agriculture, where many farmers lack sufficient capital to invest in their operations, credit plays a vital role. Farmers often require short-term loans to fund crop cultivation and address immediate consumption needs, as well as medium-term loans for asset replacement and maintenance. The utilization of credit varies among borrowers depending on their specific circumstances. In designated districts, Lead Banks are expected to play a pivotal role in fostering banking and credit development. A significant portion (55.00 percent) of respondents exhibit a high level of credit utilization, with medium and low levels accounting for 22.50 percent each. The majority of loan recipients (84.17 percent) are categorized as Regulars, while 15.83 percent are labeled as Defaulters. The primary expenditures for loan funds among respondents include seed procurement (ranked first), followed by fertilizer purchases (second), and spending on herbicides, pesticides, and other chemicals (third). This indicates a preference for utilizing loan funds towards essential agricultural inputs. Among the identified patterns of credit utilization, the highest-ranked activities include frequent procurement of seeds (1st rank), followed by fertilizer purchases (2nd rank), and spending on herbicides, pesticides, and other chemicals (3rd rank).
Summary
Source-checkedPlain-language reading of the full paper, prepared with AI and checked against the text. Each point links to the authors' own words.
Why it matters
- Credit is essential in agriculture because many farmers do not have enough capital to invest in their farming operations. View evidence ↗
- Farmers typically use short-term loans for crop cultivation and consumption, and medium-term loans for maintaining or replacing assets. View evidence ↗
- Loan repayment behavior is a key indicator of a farmer's ability to generate income and their commitment to financial obligations. View evidence ↗
The question
- The study aimed to examine how agriculture loan borrowers from a lead bank in the Pune district utilize their credit and behave regarding repayment. View evidence ↗
What they did
- The researchers purposively selected the Baramati and Indapur Tehsils in Pune District, then chose five villages per Tehsil and randomly selected 12 beneficiary farmers from each village. View evidence ↗
- Data were gathered through personal interviews with a total of 120 beneficiary farmers using a structured interview schedule. View evidence ↗
What they found
- The majority of respondents (55.00%) were categorized as having a medium level of credit utilization (scores between 17.78 and 21), although the text also inconsistently refers to this as a 'high level'. View evidence ↗
- Equal proportions of respondents (22.50% each) exhibited low (up to 17.78) and high (above 21) levels of credit utilization. View evidence ↗
What it means
- The authors conclude that farmers utilize credit prudently and purposefully, which supports the productivity and sustainability of agricultural practices. View evidence ↗
Visual summary
2 visualsIllustrations explain the paper; charts are replotted from the paper's own table values.
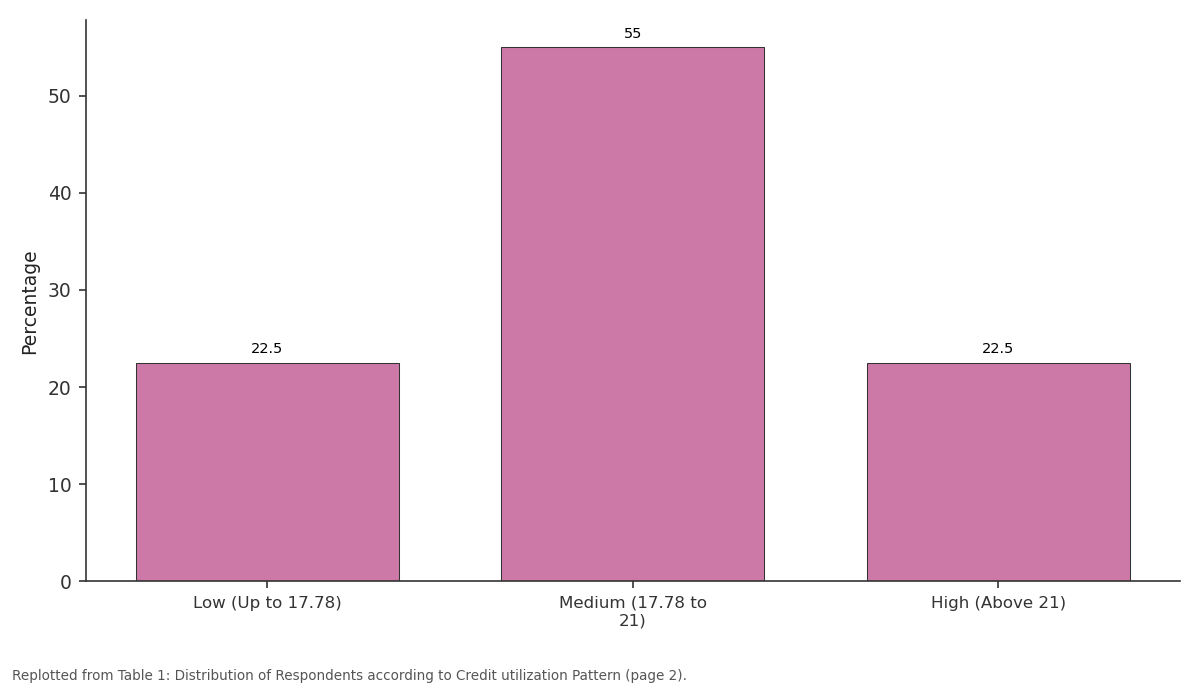
Percentage: Low (Up to 17.78) vs Medium (17.78 to 21) vs High (Above 21)
Replotted from Table 1 (page 2) of the original paper. Every bar is the paper's own table value.
View source evidence ↗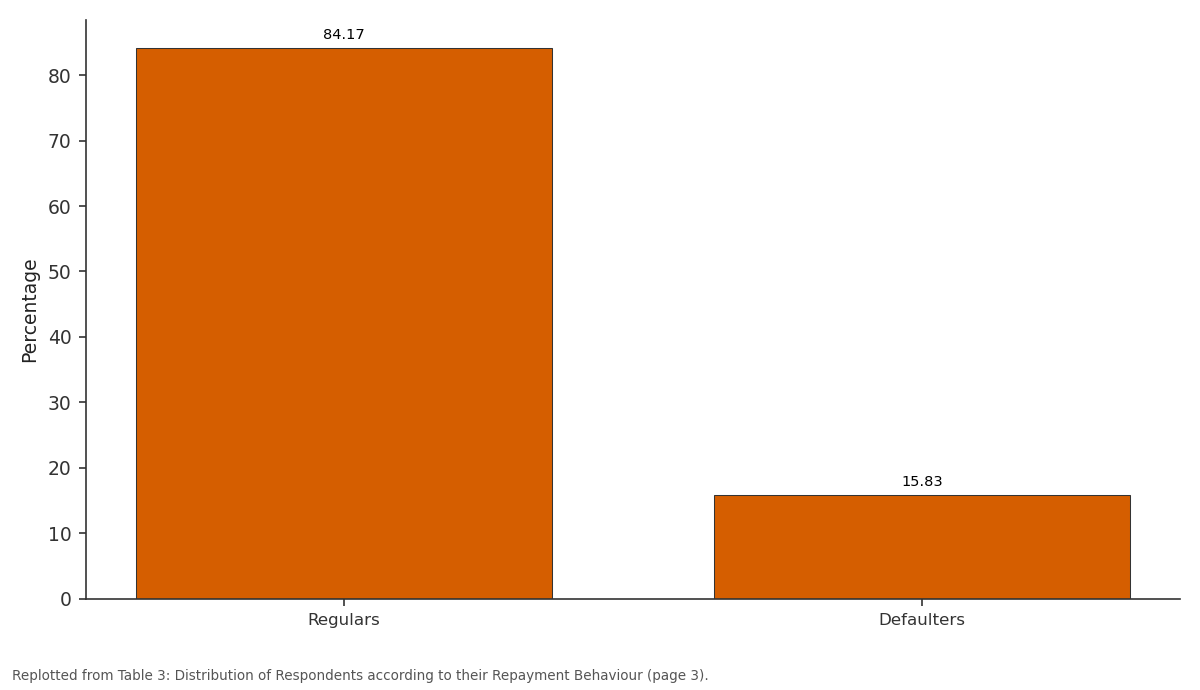
Percentage: Regulars vs Defaulters
Replotted from Table 3 (page 3) of the original paper. Every bar is the paper's own table value.
View source evidence ↗Figures & tables
From the original paper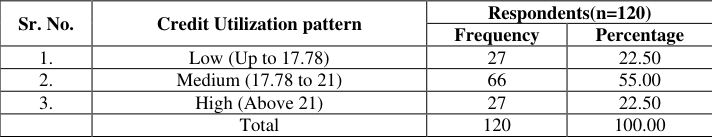 Table 1
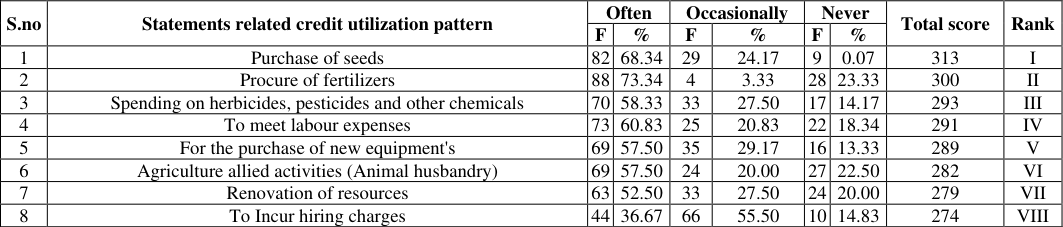 Table 2
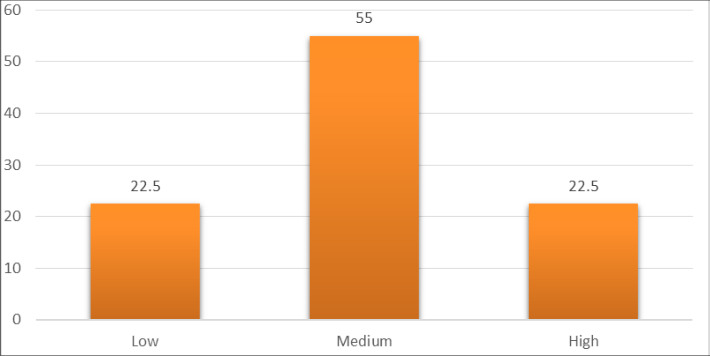 Figure 1
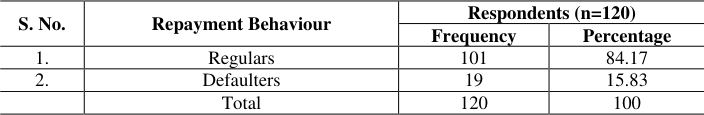 Table 3
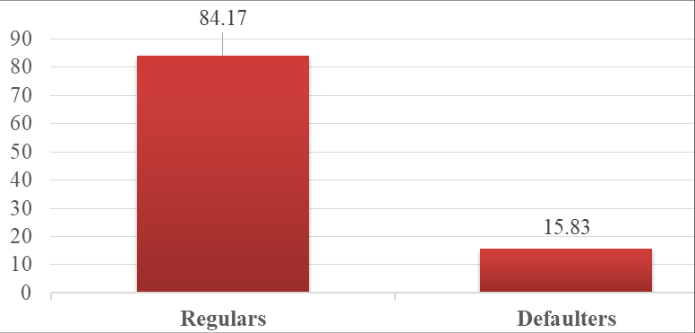 Figure 2
Introduction
In agriculture, farmers commonly rely on loans to finance various aspects of their operations, including seed purchases, equipment acquisition, and operational expenses. The utilization pattern of credit in this sector revolves around how farmers manage and deploy the credit extended to them, mainly through loans. The repayment behavior associated with these loans holds significant importance for both farmers and lenders. It serves as an indicator of the farmers' capacity to generate income from agricultural activities and their dedication to meeting financial obligations. For lenders, repayment behavior acts as a critical gauge of creditworthiness. A favourable credit utilization pattern for farmers entails the prudent use of credit to boost agricultural productivity and income, coupled with prompt repayments. This not only aids in establishing a positive credit history but also paves the way for accessing larger credit facilities in the future. Conversely, an unfavorable credit utilization pattern characterized by delayed or missed payments can lead to adverse consequences. These may include heightened interest costs, difficulties in securing future loans, and a detrimental impact on the overall financial well-being of the farming enterprise. Effective comprehension and management of credit utilization patterns, alongside maintaining a robust repayment behaviour, are fundamental for fostering sustainable agricultural practices and ensuring financial stability within the farming community.
Materials and Methods
An Ex post facto research design was used to study the credit utilization pattern and repayment behavior of agriculture loan borrowers of lead bank in Pune district.Ex post facto is a Latin phrase that essentially means "retroactive" or affecting something that's already happened. (Kerlinger, F. N. (1964) [2] . In Pune District, there are a total of 14 Tehsils. Among them, Baramati and Indapur were chosen purposively due to their higher number of loan beneficiaries. Five villages were purposively selected from each Tehsil based on the presence of loan beneficiaries. From each of these villages, 12 beneficiary farmers were randomly chosen. The structured interview schedule was prepared keeping in view of the objectives of the study. The pattern of credit utilization was operationalized as the way the loan was spent on various agricultural operations. The variable was measured with the help of schedule developed by consulting the experts and reviews with help of advisory committee members and study of Shashikant Divakar (2013) [6] . The schedule contained of 8 statements. The respondents were requested to rate each statement on three point continuum viz., often, occasional and never with scoring of 3, 2 and 1 www.extensionjournal.com respectively. The total score of each respondent was worked out by summing up scores of all statements. Further, the respondents were grouped into three categories as below by using Mean and ± SD.Data were collected by personally interviewing 120 Beneficiary farmers with the help of interview schedule. In Table 1, the data reveals that the majority (55.00 percent) of respondents exhibited a high level of credit utilization pattern. Following this, 22.50 percent each indicated a medium and low level of utilization pattern for loans.
| Sr. No. | Credit Utilization pattern | Respondents(n=120) | — |
|---|---|---|---|
| Frequency | Percentage | ||
| 1. | Low (Up to 17.78) | 27 | 22.50 |
| 2. | Medium (17.78 to 21) | 66 | 55.00 |
| 3. | High (Above 21) | 27 | 22.50 |
| Total | 120 | 100.00 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
Results and Discussion
The preference for a medium credit utilization pattern over high or low among farmers can be attributed to their conscientious approach in utilizing borrowed funds for specific purposes. These purposes include the procurement of seeds, fertilizers, pesticides, meeting labor charges, resource renovation, hiring charges, acquiring new equipment, and engaging in animal husbandry. Given that the available loan amount was earmarked primarily for agricultural purposes, farmers tended to allocate funds accordingly, without deviating towards non-productive or unspecified uses such as personal or household expenses. This rationale contributes to the observed medium percentage in credit utilization pattern. Interestingly, these findings align closely with those of Shashikant Divakar (2013) [6] , indicating consistency in trends across studies. According to Table 2, the analysis reveals that the majority of respondents allocated their loan funds primarily towards seed procurement (ranked first), followed by fertilizer purchases (ranked second), and expenditure on herbicides, pesticides, and other chemicals (ranked third). Subsequent expenditure categories included labor costs, purchasing new equipment, engaging in agriculture-related activities such as animal husbandry, resource renovation, and incurring hiring charges. This pattern suggests that among the eight statements regarding credit utilization, the highest-ranked activities were consistently those related to the procurement of seeds, followed by fertilizer purchases and spending on herbicides, pesticides, and other chemicals. This trend could be attributed to farmers' habitual tendency to allocate a significant portion of their available loan towards seed procurement, thus prioritizing this essential aspect of their agricultural operations. www.extensionjournal.com The data presented in Table 3 indicates that the vast majority of loan-borrowing farmers, comprising 84.17 percent, fall under the category of "Regulars," while the remaining 15.83 percent are classified as "Defaulters." This finding corroborates the results reported by Reena Rawat (2016) [4] , confirming a similar distribution pattern observed in previous studies.
| S. No. | Repayment Behaviour | Respondents (n=120) | — |
|---|---|---|---|
| Frequency | Percentage | ||
| 1. | Regulars | 101 | 84.17 |
| 2. | Defaulters | 19 | 15.83 |
| Total | 120 | 100 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
| S.no | Statements related credit utilization pattern | Often | — | Occasionally | — | Never | — | Total score | Rank |
|---|---|---|---|---|---|---|---|---|---|
| F | % | F | % | F | % | ||||
| 1 | Purchase of seeds | 82 | 68.34 | 29 | 24.17 | 9 | 0.07 | 313 | I |
| 2 | Procure of fertilizers | 88 | 73.34 | 4 | 3.33 | 28 | 23.33 | 300 | II |
| 3 | Spending on herbicides, pesticides and other chemicals | 70 | 58.33 | 33 | 27.50 | 17 | 14.17 | 293 | III |
| 4 | To meet labour expenses | 73 | 60.83 | 25 | 20.83 | 22 | 18.34 | 291 | IV |
| 5 | For the purchase of new equipment's | 69 | 57.50 | 35 | 29.17 | 16 | 13.33 | 289 | V |
| 6 | Agriculture allied activities (Animal husbandry) | 69 | 57.50 | 24 | 20.00 | 27 | 22.50 | 282 | VI |
| 7 | Renovation of resources | 63 | 52.50 | 33 | 27.50 | 24 | 20.00 | 279 | VII |
| 8 | To Incur hiring charges | 44 | 36.67 | 66 | 55.50 | 10 | 14.83 | 274 | VIII |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
Conclusion
The analysis of the data presented in Tables 1,2, and 3 sheds light on several key insights regarding credit utilization patterns among farmers. Firstly, a significant majority of respondents demonstrated a high level of credit utilization, indicating a conscientious approach towards utilizing borrowed funds for specific agricultural purposes. This finding aligns with previous studies and underscores the importance of earmarking loan amounts primarily for agricultural activities. Secondly, the allocation of loan funds was predominantly directed towards essential agricultural inputs such as seed procurement, fertilizer purchases, and expenditure on herbicides, pesticides, and other chemicals. This consistent prioritization reflects farmers' habitual tendencies to prioritize these crucial aspects of their operations. Finally, the classification of loan-borrowing farmers into "Regulars" and "Defaulters" further emphasizes the importance of adherence to repayment schedules, with the majority falling under the category of "Regulars." Overall, these findings highlight the prudent and purposeful utilization of credit among farmers, contributing to the sustainability and productivity of agricultural practices.
Figures and tables from the paper
References
0 in the original paperCited by 7
From OpenAlex, OpenCitations and reference lists read by Scinovex
- Constraints in credit accessibility from primary agricultural cooperative societies in Haryana state, India ↗
Suninder Singh, Abhey Singh, Choote Lal · Economic and Regional Studies / Studia Ekonomiczne i Regionalne · 2023
Abstract Subject and purpose of work: The objective of the study was to identify the constraints in credit accessibility from Primary Agricultural Cooperative Societies in Haryana State, India. Materials and methods: The primary data were used for achieving the objective of the study. The primary data were collected in the second quarter of 2022 by employing the schedule. The multistage…
❝ 3PDF - Loan repayment behavior of beneficiary farmers in primary agricultural cooperative societies in Haryana (India) ↗
Suninder Singh, Abhey Singh, Sumista Rani, Mamta Rani · Economic and Regional Studies / Studia Ekonomiczne i Regionalne · 2024
Abstract Subject and purpose of work The study examined the loan repayment behavior of beneficiary farmers in Primary Agricultural Cooperative Societies in the State of Haryana, India. Material and methods The findings were based on primary as well as secondary data. The secondary data was collected for the period of 2006-2007 to 2018-2019. The primary data was collected in the…
❝ 1PDF - The Agri-credit accessibility and the utilization of Agri-loan proceeds of rice farmers ↗
Kaye Moreno Villena, Gerlyn Escalona Manalo, Glaizy Myll Batan Ramirez, Renzo Sanchez Consul, Joshua Esclavia Vallada, Russell Villena Villarma · World Journal of Advanced Research and Reviews · 2024
Rice farmers struggle to obtain and effectively utilize credit, which limits their agricultural productivity and livelihood. This study examined the relationship between agri-credit accessibility and utilization of agri-loan proceeds among the 59 registered rice farmers in Villa Cerveza, Victoria, Oriental Mindoro. It aimed to assess the extent of accessibility of agri-credit from microfinance institutions, banking institutions, and informal lenders and…
❝ 1PDF - Utilisation patterns and repayment behaviour of agricultural borrowers: Evidence from a regional rural bank in Darrang district of Assam ↗
Himakshi Jain, Balin Hazarika · Asian Journal of Management and Commerce · 2026
The present paper assesses the loan utilisation and repayment behaviour of farmers from a rural bank in the Darrang district. Primary data were collected from 130 farmers using an interview schedule and a random sampling method was applied to select the sample. Further, percentage analysis and the chi-square test were used to analyse the data. The findings of the study
- Credit utilization pattern of cotton growers in Yavatmal district
SP Zadokar, NV Shende, RD Vaidkar, SP Lambe · International Journal of Agriculture Extension and Social Development · 2026
The present study was undertaken during the agricultural year 2025–26 to examine the credit requirements and utilization pattern, debt burden and factors influencing credit utilization among cotton growers in Yavatmal district. A multistage random sampling technique was adopted, and 120 cotton growers were selected from Yavatmal, Darwha and Kalamb tehsils. Primary data were collected through personal interviews using a pre-tested questionnaire. Tabular analysis and multiple regression analysis technique were employed for analysis. The overall credit requirement for cotton cultivation was Rs. 6
- Loan borrowing pattern and factors influencing agricultural loan borrowing among soybean farmers in Washim district
Reshma R Jadhao, Sangita V. Warade, NV Shende, PR Kadu · International Journal of Agriculture and Food Science · 2026
The present paper entitled “Loan Borrowing Pattern and Factors Influencing Agricultural Credit among Soybean Farmers in Washim District” was undertaken to study the loan borrowing pattern and utilization of agricultural credit and to identify the factors encouraging soybean farmers to borrow loans. The study was conducted during the agricultural year 2024-25 in Washim district of Maharashtra. Primary data were collected from 90 selected soybean farmers through personal interviews using a pre-tested and structured schedule. The respondents were selected from nine villages of Washim, Risod and M
- Loan utilization pattern and constraints faced by paddy farmers in Chandrapur district
Sakshi D Khobragade, Sangita V. Warade, NV Shende, PR Kadu · International Journal of Agriculture and Food Science · 2026
The present paper was undertaken to examine the loan borrowing pattern, utilization of agricultural credit, and constraints faced by paddy farmers in Chandrapur district of Maharashtra. Primary data were collected from 90 selected paddy farmers during 2024–2025 through personal interviews using a structured questionnaire. The data were analyzed using tabular and percentage analysis. The findings revealed that institutional sources were the major sources of agricultural credit, with co-operative societies accounting for the highest share of borrowing (35.56%), followed by commercial banks (31.1