
Research article · 2018 · Full text
International Journal of Agriculture Extension and Social DevelopmentPerformance of RRB in relation to agriculture
Volume 1(2) · Pages 26–28 · DOI: 10.33545/26180723.2018.v1.i2a.84 ↗
Research areasMicrofinance and Financial InclusionFinTech, Crowdfunding, Digital FinanceIslamic Finance and Banking Studies
Abstract
Author-writtenRegional Rural Banks (RRBs) were set up as state-sponsored, regionally based and rural oriented institutions under the Regional Rural Banks Act, 1976. The main aim or idea of establishing RRB is to meet credit needs of rural people. The objective to establish the RRB was To provide advances to small & marginal farmers, agricultural labourers & small entrepreneurs who are engaged in agricultural business. To provide loan facilities to Cooperative societies, which are engaged on services related to rural area including agriculture activities. To convert the rural savings (by accepting deposits) into the productive activities in rural areas by Using that money in agricultural activities. The share of the RRB in Ground level credit increases from 9.2 (2009-10) to 11.6 (2013-14). In relation to disburse the loan to small farmers and Marginal farmers the percentage share to total credit disbursed by RRB is 62.14.
Summary
Source-checkedPlain-language reading of the full paper, prepared with AI and checked against the text. Each point links to the authors' own words.
Why it matters
- Regional Rural Banks (RRBs) were established under the Regional Rural Banks Act of 1976 as state-sponsored institutions focused on rural areas. View evidence ↗
- The primary purpose of creating RRBs is to address the credit requirements of people living in rural regions. View evidence ↗
- RRBs specifically aim to provide financial advances to agricultural laborers, small and marginal farmers, and small entrepreneurs in the agricultural sector. View evidence ↗
The question
- The study aims to examine the flow of credit directed toward agriculture. View evidence ↗
- The study intends to investigate the outstanding loans of RRBs categorized by their purpose. View evidence ↗
What they did
- The research methodology relies on secondary data sourced from NABARD annual reports, websites, reports, and various articles. View evidence ↗
What they found
- The share of RRBs in ground-level credit grew from 9.2% in 2009-10 to 11.6% in 2013-14. View evidence ↗
- RRBs disbursed 62.14% of their total credit specifically to small and marginal farmers. View evidence ↗
- The expansion of branch networks has led to increased overhead costs without a corresponding increase in profit. View evidence ↗
- Because RRBs target the poor, there is low deposit mobilization as these clients have limited savings to deposit. View evidence ↗
What it means
- The author recommends merging RRBs with commercial banks to improve viability and reduce accumulated insolvency losses. View evidence ↗
- The author suggests streamlining recruitment by prioritizing local candidates and providing proper employee training. View evidence ↗
Visual summary
1 visualsIllustrations explain the paper; they do not show study data.
RRB Credit Ecosystem
AI-generated conceptual illustration (Rural bank building and small-scale farmers in a rural agricultural landscape). It explains the idea and does not show study data.
View source evidence ↗Figures & tables
From the original paper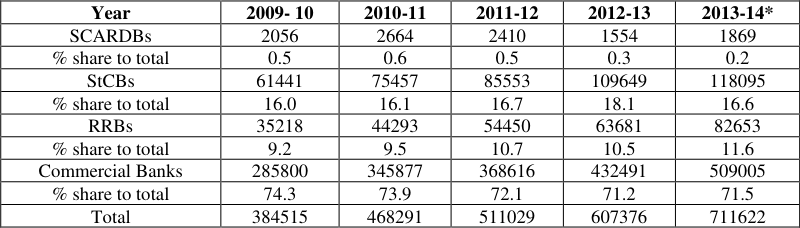 Table 1
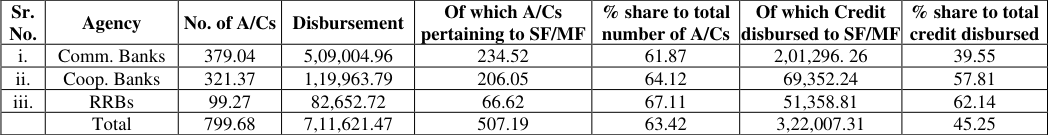 Table 2
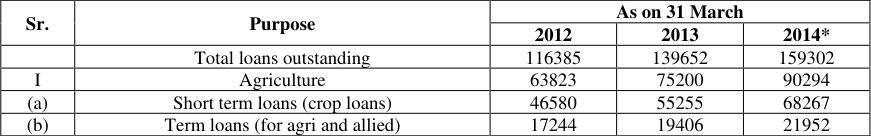 Table 3
Introduction
Regional Rural Banks (RRBs) were set up as statesponsored, regionally based and rural oriented institutions under the Regional Rural Banks Act, 1976. In September, 2005, GoI initiated the first phase amalgamation of RRBs, sponsor bank-wise, at state level. By March, 2010, RRBs of the same sponsor banks within a State were amalgamated bringing down their number from 196 to 82. In the second and ongoing phase, starting from October, 2012, geographically contiguous RRBs within a State under different sponsor banks are being amalgamated to have just one RRB in medium-sized and two/three RRBs in large states. During the year 2013-14, 13 RRBs have been amalgamated into 6 new RRBs in 5 States (Chhattisgarh, Uttar Pradesh, Kerala, Karnataka and Haryana). With this, the effective number of RRBs as on 31st March, 2014 stands at 57 playing a significant role in developing agriculture and rural economy. The review of the performance of RRBs as on 31st March, 2014 reveals that the RRBs have responded well to the initiatives taken by GoI.
Objective
1. To study the credit flow to agriculture 2. To study the financial estimation of loan disburse to small/ marginal Farmers 3. To study about the purpose wise outstanding by RRB
Research Methodology
This paper is based on the secondary data and drained from annual reports of NABARD and from various articles, reports, and websites.
Objectives and Functions of Regional Rural Banks
The main aim or idea of establishing RRB is to meet credit needs of rural people. There are some other objectives of RRBs are 1. To provide advances to small & marginal farmers, agricultural labourers & small entrepreneurs who are engaged in agricultural business. 2. To provide banking facilities to rural areas specially unbanked area. 3. To provide loan facilities to Cooperative societies, which are engaged on services related to rural area including agriculture activities. 4. To increase the golden opportunities of employment in RRBs which creates employment at their door step for rural people. 5. Some other auxiliary functions of RRBs ▪ To convert the rural savings (by accepting deposits) into the productive activities in rural areas by Using that money in agricultural activities. ▪ Now a day's RRBs starts providing loans for purchasing durable goods against the security of gold, NSC etc. ▪ *Another new facility provided by RRBs is to issue guarantee on the behalf of their customer #100% cash margin up to 20lakhs Above 20lakhs up to 40lakhs cash margin + collateral security of more than 50%
Credit Flow in Agriculture
The total credit flow to agriculture, agency-wise, during the last 5 year period by all agencies is as under: www.extensionjournal.com But with the transfer of recruitment on RRB's to banking services recruitment boards, all the candidate outside the area of cooperation of RRB's eligible for RRB's . This is against the concept of RRB's.
Suggestions To Improve Regional Rural Banks
Working 1. To improve the RRB's some parties take initiative for this and provide some solutions to the problems. 1. The important thing for existence there is the requirement of feasibility and viability of the organisation. For this there is the recommendation that RRB's should be merged with commercial banks. It will help to reduce the accumulated losses of insolvency of the banks. This solution is helpful for some RRB's only. 2. Mobilisation of funds or converting the savings of rural people in productive activity can be removed by using the funds transfer from urban to rural area with the help of govt. policies. State govt. about permit the Panchayat & other quasi govt. to keep their funds with RRB's in that area. 3. To reduce the cost of RRB's state govt . either reorganize agricultural credit societies on establish other societies through which RRB's increase their production credit on large scale and use the economies of scale in efficient manner. Another way to reduce the cost of loan is to reduce transaction cost of providing loan to the rural people. www.extensionjournal.com 4. The recruitment process in RRB's should be streamlined. There should be preference to the local people and also provide proper training about the work to employees. And also there should be uniform pay scale for employees. 5. To handle with the problem of huge expansion of branches, there should be expansion of no. of employees to handle the work load. And for supervision on the RRB'S there should be the proper authority that manage and control the working of RRB'. One another method for effective working is to reduce the commercial bank branches in the rural area and hand over these branches to RRB's. 6. The main issue related with the banking system is rigid norms, there is less flexibility in the regulation system which can make the huge hindrance I'm the working of RRB's. To overcome with this problem there should be some free hand for RRB's. Some concession should be given to RRB's according to the area side or department wise according to the need of the RRB. Because at present rules are made by the authority for whole India without differentiation about the state.
Figures and tables from the paper
| Year | 2009- 10 | 2010-11 | 2011-12 | 2012-13 | 2013-14* |
|---|---|---|---|---|---|
| SCARDBs | 2056 | 2664 | 2410 | 1554 | 1869 |
| % share to total | 0.5 | 0.6 | 0.5 | 0.3 | 0.2 |
| StCBs | 61441 | 75457 | 85553 | 109649 | 118095 |
| % share to total | 16.0 | 16.1 | 16.7 | 18.1 | 16.6 |
| RRBs | 35218 | 44293 | 54450 | 63681 | 82653 |
| % share to total | 9.2 | 9.5 | 10.7 | 10.5 | 11.6 |
| Commercial Banks | 285800 | 345877 | 368616 | 432491 | 509005 |
| % share to total | 74.3 | 73.9 | 72.1 | 71.2 | 71.5 |
| Total | 384515 | 468291 | 511029 | 607376 | 711622 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
| Sr. No. | Agency | No. of A/Cs | Disbursement | Of which A/Cs pertaining to SF/MF | % share to total number of A/Cs | Of which Credit disbursed to SF/MF | % share to total credit disbursed |
|---|---|---|---|---|---|---|---|
| i. | Comm. Banks | 379.04 | 5,09,004.96 | 234.52 | 61.87 | 2,01,296. 26 | 39.55 |
| ii. | Coop. Banks | 321.37 | 1,19,963.79 | 206.05 | 64.12 | 69,352.24 | 57.81 |
| iii. | RRBs | 99.27 | 82,652.72 | 66.62 | 67.11 | 51,358.81 | 62.14 |
| Total | 799.68 | 7,11,621.47 | 507.19 | 63.42 | 3,22,007.31 | 45.25 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
| Sr. | Purpose | As on 31 March | — | — |
|---|---|---|---|---|
| 2012 | 2013 | 2014* | ||
| Total loans outstanding | 116385 | 139652 | 159302 | |
| I | Agriculture | 63823 | 75200 | 90294 |
| (a) | Short term loans (crop loans) | 46580 | 55255 | 68267 |
| (b) | Term loans (for agri and allied) | 17244 | 19406 | 21952 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
References
2 in the original paper- Burgess, Robin, Rohini Pande. "Do rural banks matter? Evidence from the Indian social banking experiment." American Economic Review 2005;95(3):780-795.
- Varman, Mahendra. "Impact of self-help groups on formal banking habits." Economic and Political Weekly 2005, 1705-1713.