
Research article · 2020 · Full text
International Journal of Statistics and Applied MathematicsDoes Nigeria economic growth benefit from domestic borrowing? econometric modelling approach
Volume 5(2) · Pages 80–88
Research areasFiscal Policy and Economic Growth
Abstract
Author-writtenThe paper examines whether Nigeria’s economic growth benefit from domestic borrowing. Time series data collected on domestic debt (DD) outstanding and real gross domestic product (RGDP) span from 1981 to 2018. Using regression with lagged exogenous, Vector autoregressive (VEC) model and Granger causality test, the results reveal that DD exacts positive effect on economic growth only at lag 1 and lag2, significant under 5% level; there is long-run relationship between DD and economic growth, and unilateral granger causality flows from DD to economic growth both in short-run and long-run. Therefore, it is advisable for the government to consider domestic window when there is necessity to borrow rather than external window for the benefit of economic growth.
Summary
Source-checkedPlain-language reading of the full paper, prepared with AI and checked against the text. Each point links to the authors' own words.
Why it matters
- Governments use internal and external borrowing to fund capital projects and supplement revenue for debt servicing. View evidence ↗
- Domestic debt in Nigeria has grown significantly to 12,774.40 billion naira, with only a minor 12.1% drop occurring in 1996. View evidence ↗
- Existing literature on the relationship between domestic borrowing and economic growth in Nigeria is insufficient and often contradictory. View evidence ↗
The question
- The study aims to determine if domestic borrowing benefits Nigeria's economic growth. View evidence ↗
What they did
- The researchers used time series data for domestic debt (DD) and real gross domestic product (RGDP) from 1981 to 2018. View evidence ↗
- The analysis employed a Vector Error Correction (VEC) model, regression with lagged exogenous variables, and Granger causality tests. View evidence ↗
- Real gross domestic product (RGDP) was used as the proxy for economic growth to test the effects of domestic borrowing over time. View evidence ↗
What they found
- Approximately 37.2% of the variation in Nigeria's economic growth is explained by domestic debt when considering a time lag of up to three years. View evidence ↗
- A long-run relationship exists between domestic debt and real gross domestic product, as indicated by a trace statistic of 54.86043 exceeding the 5% critical value of 25.87211. View evidence ↗
- Long-run Granger causality flows from domestic debt to RGDP, but not vice versa, supported by a significant t-statistic of 5.22346 for the error correction term. View evidence ↗
- Unidirectional Granger causality flows from domestic debt to economic growth up to the 7th lag, with all p-values significant under the 5% level. View evidence ↗
What it means
- The authors conclude that domestic debt has a significant positive effect on economic growth in both the short and long run, typically after a 1 to 2 year delay. View evidence ↗
- The authors recommend that the Nigerian government prioritize domestic borrowing over external borrowing to benefit economic growth. View evidence ↗
Figures & tables
From the original paper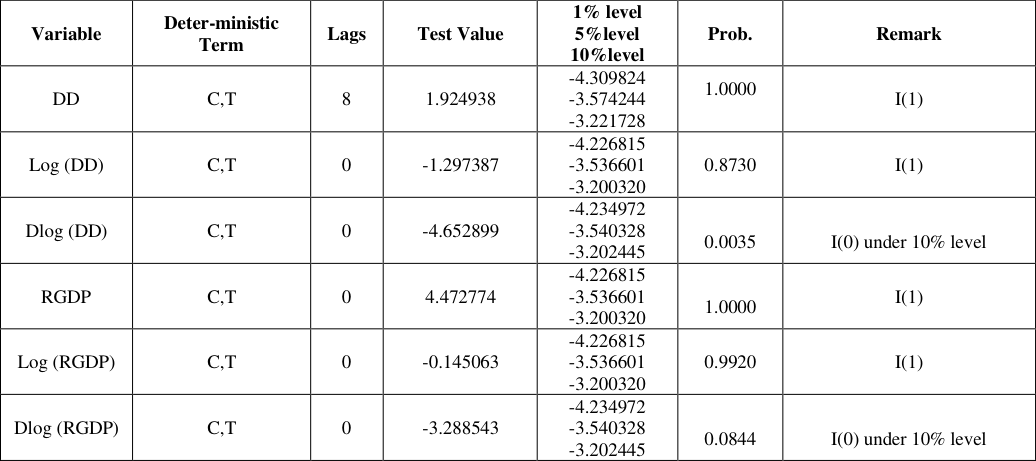 Table 1
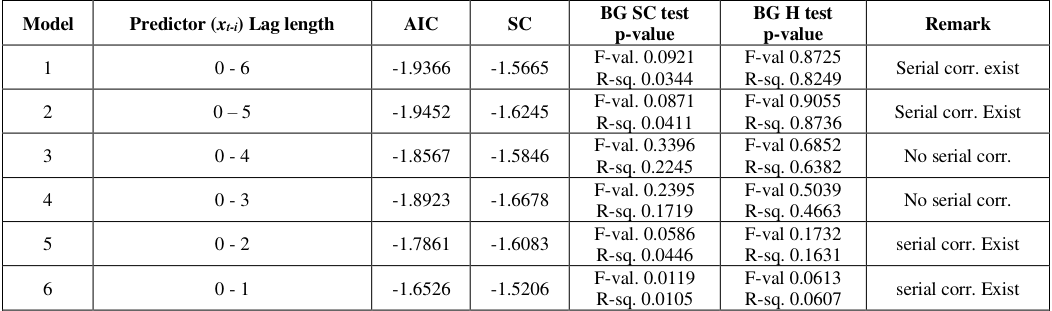 Table 2
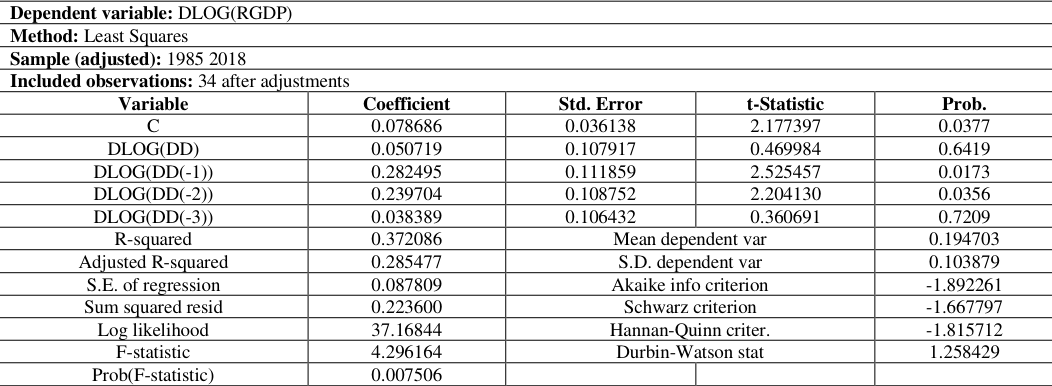 Table 3
 Table 4
 Table 5
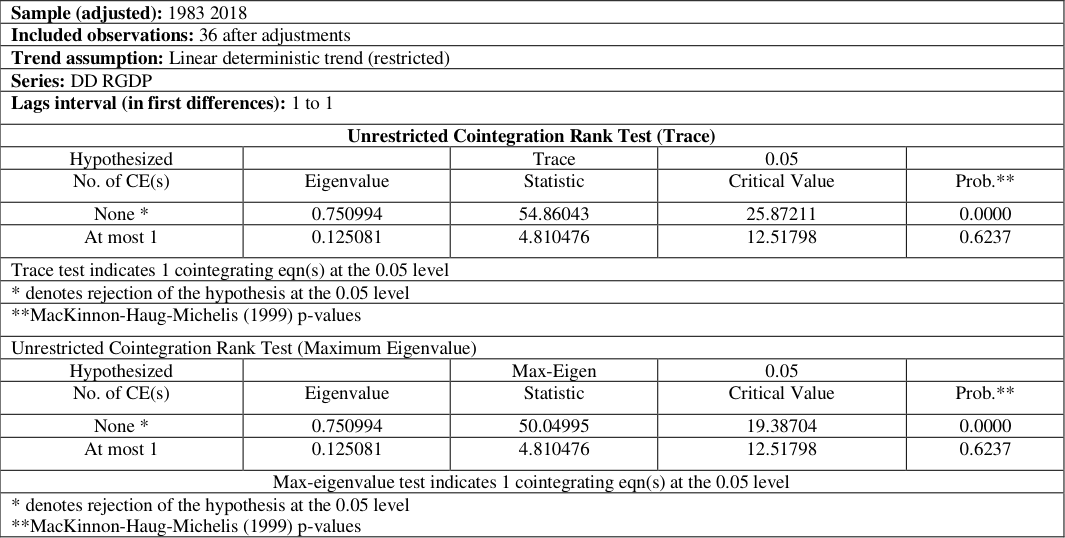 Table 6
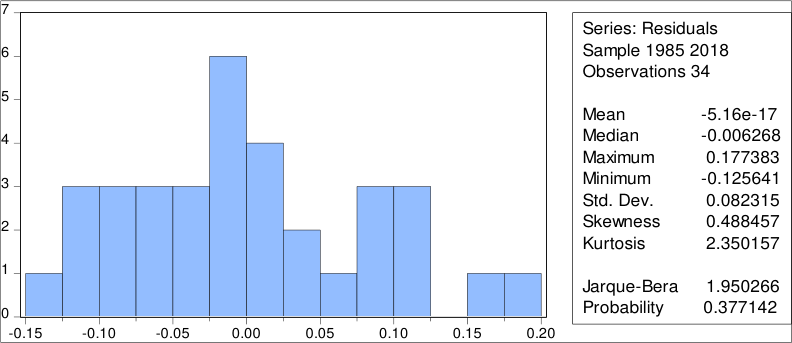 Figure 1
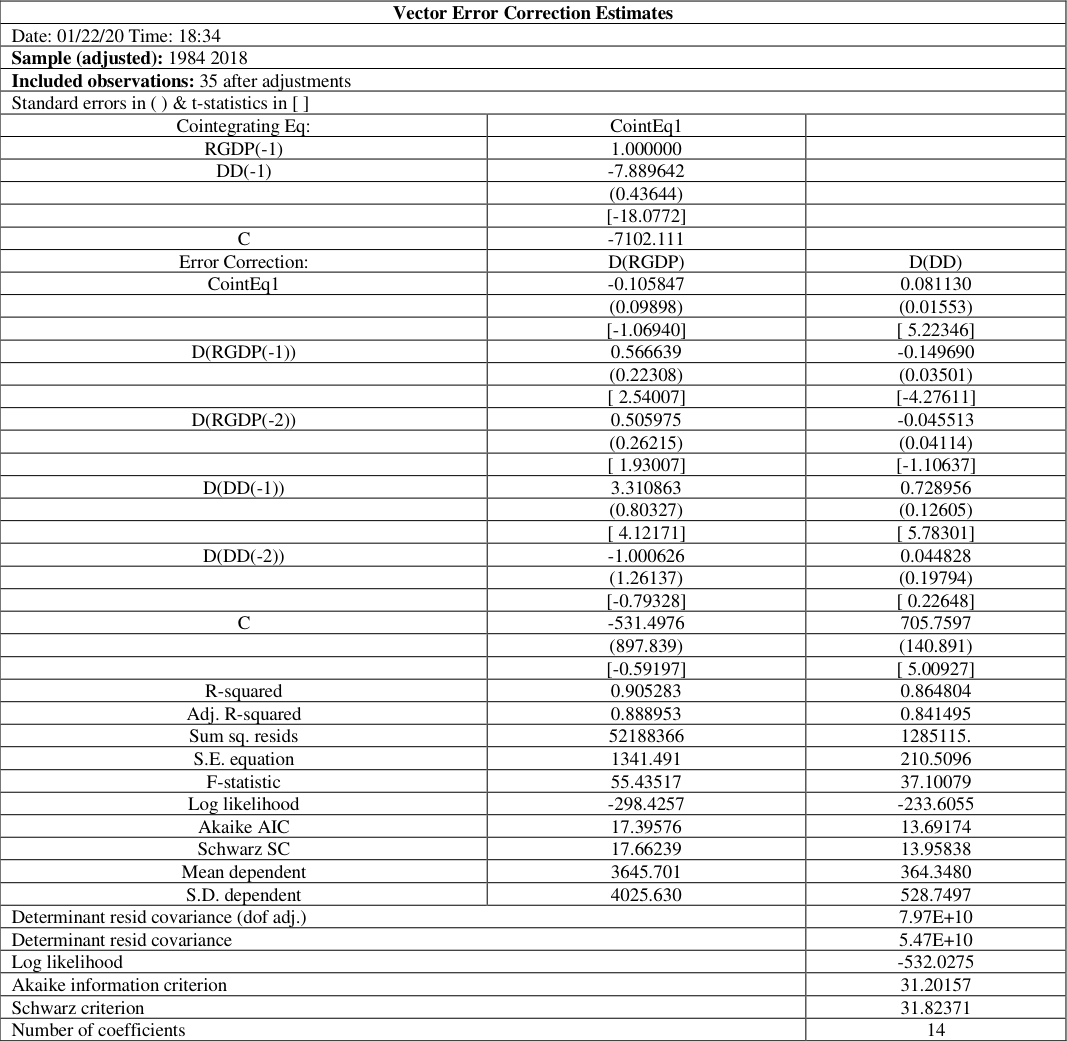 Table 7
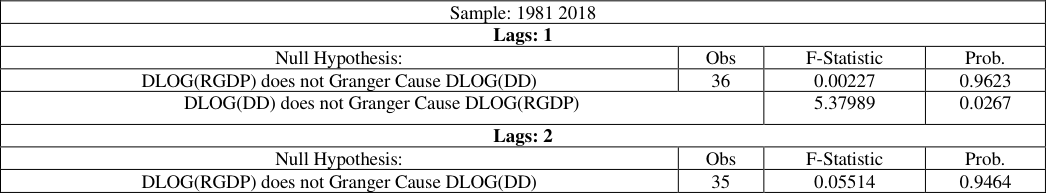 Table 8
Introduction
Domestic Debts are debts that originate from within the geographical region of a country, which are contracted through debt instruments such as treasury bills, treasury certificates and treasury bonds. Others are development stocks, FGN bonds and Promissory notes. The essence of government borrowing whether internal or external is to finance capital projects and some time to augment internally generated revenue for debt servicing. When Government borrows internally via domestic window, it means that government is choosing easier debt servicing condition. Based on data available as published by CBN statistical bulletin (2018), domestic debt in Nigeria has consistently increased apart from in 1996 when there was a little drop in domestic debt outstanding to about 419.98 million, accounting for approximately 12.1% drop in domestic debt outstanding. And since then, domestic debt has increased tremendously up to the tune of 12,774.40 billion naira. What implication has this on the economic growth of Nigeria. There is no doubt that Nigeria is not a special case regarding its increasing domestic debt. Governments of other countries also do borrow to finance budget deficit but since Nigerian economy slipped into recession in 2016, different questions have risen as to what extent has the country's consistent increasing debts outstanding helped the economy to grow. Different studies on the relationship between domestic debt and economic growth has been carried out by researchers both in developed and developing countries. Fry (1997) [6] studies the impact of alternative deficit financing strategies on economic growth for sixty six lowincome countries and emerging markets for the period of 1979-1993. The study shows that market based domestic debt issuance is the least cost method of financing the budget deficit as contrasting with external borrowing and seignorage. All of these methods reduce growth, domestic savings and increase inflation. Singh (1999) [14] explores the relationship between domestic debt and economic growth in India by applying co integration technique and Granger causality test for the period of 1959-95. The author considers two theoretical views of domestic debt and economic growth one is traditional view of long-run negative impacts of domestic debt on economic growth and second is Ricardian Equivalence hypothesis that shows neutrality of domestic debt to growth. The results of the Engle-Granger co integration test indicate that the domestic debt and economic growth are not co-integrated. The study supports the Ricardian equivalence hypothesis between domestic debt and growth in India. Kemal (2001) [9] explains the debt accumulation and its implications for growth and poverty in Pakistan. The study shows that debt accumulation (domestic and external) and debt servicing affects the poor adversely. The findings of the study illustrate that even though debt burden as a percentage of GDP of Pakistan exceeds that of all South Asian countries but it is not still so high as to go for debt write off. This means that Pakistan has the capacity to service the debt. Uzochukwu (2003) [16] investigates the quantitative effects of public debt (domestic and external) and economic growth on poverty in Nigeria by applying the per-capita income approach using annual data of 1970 to 2002. The study uses growth and debt variables and suggests that these variables have played very vital role towards poverty acceleration in Nigeria. Schclarek (2004) [13] observes the relationship between gross government debt and per capita GDP growth in developed countries. The results of the paper show that there is no strong evidence of a statistically significant relationship between gross government debt and per capita GDP growth for a sample of 24 industrial countries with data from 1970 to 2002. Abbas and Christensen (2007) [2] highlight the impact of domestic debt on economic growth for ninety-three low-income countries from the period of 1975-2004 by applying Granger Causality Regression model. The analysis shows that moderate levels of marketable domestic debt as a percentage of GDP have significant positive, non-linear impacts on economic growth, but debt levels exceeding thirty five percent of total bank deposits have negative impact on economic growth. Maana et al. (2008) [10] analyze the economic impact of domestic debt on Kenya's economy. Authors examine the impacts of domestic debt on private sector lending by applying ordinary least square technique using annual data over the period 1996 to 2007. The study revealed that domestic debt does not crowd out private sector lending in Kenya during the period due to substantial level of financial development in Kenya. The study also examined the effects of domestic debt on real output by using a modified Barro growth regression model (Barro,1974). The results indicate that increase in domestic debt has a positive but insignificant effect on economic growth during the period. The study suggests that government should employ wider reforms that promote investment in treasury bonds and encourage institutional investors. Adoufu and Abula (2010) [1] investigate the effects of rising domestic debt on the Nigerian economy by applying OLS technique using time series data from 1986-2005. The findings of the study reveal that several factors responsible for rising domestic debt in Nigeria are high budget deficit, low output level, increased government expenditures, high inflation rate and narrow revenue base. The analysis shows that domestic debt has negatively affected the growth of the economy and recommends that government should made efforts to resolve the outstanding domestic debt. Muhammad et al. (2010) [11] studied the impacts of domestic debt on economic growth in Pakistan applying the OLS technique for the period of 1972 to 2009. The study indicates that the stock of domestic debt affects the economic growth positively in Pakistan. This clearly means that the resources generated through domestic borrowing have been used partially to finance those expenditures of government which contribute the economic growth. The study also observes that there is an inverse relationship between domestic debt servicing and economic growth. This result is due to the fact that huge burden of non-development expenditures impedes the economic growth. The findings of study reveal that the negative impact of domestic debt servicing on economic growth is stronger than positive impact of domestic debt on economic growth. Tamunonimim (2013) [15] investigated the relationship between domestic debt and the rate of poverty in Nigeria (1986-2012). Using Johansen Co-integration technique, estimated results revealed that a long-run relationship exist between poverty (measured by Gross Domestic Product, per capita gross domestic product, and basic secondary school enrolment) and domestic debt in Nigeria. The study equally revealed that the domestic debt has positive impact on bank credit and the impact is highly significant. Hence, the study recommended that government should make efforts to settle the outstanding domestic debt as it will give room for proper conduct of monetary policy in the economy. This is necessary because excessive domestic debt sometimes have negative effect on growth, if it persists. Peter et al. (2013) examined the relationship between government domestic debt and economic growth of Nigeria using unit root and co-integration test. Findings of the study showed that domestic debt and credit have significant and direct relationships with GDP, while debt servicing has an inverse relationship with GDP, and also government expenditure has a direct but insignificant relationship with GDP. The study, based on its findings, concluded that domestic debt should be invested in productive sector of the economy and more specifically in the real sector, and further productivity gain will be achieved in the improvement on capital project expenditure. Damian (2014) [4] Investigated the empirical issues pertaining to the structure and composition of domestic debt and its impact on private investment in Nigeria. The study employed multiple regression models using secondary data from 1970 to 2012. The study found that domestic debt has a significant negative impact on domestic private investment in Nigeria. Results also showed that domestic debt has a significant negative impact on foreign private investment in Nigeria with exchange rate and debt servicing having positive effect on foreign private investment in Nigeria. The study concluded that domestic debt if unchecked crowds-out private investment in Nigeria. Onogbosele and Mordecai (2016) examined the impact of domestic debt on economic growth of Nigeria for the period 1985-2014 using annual time series data on variables as gross domestic product, treasury bonds, development stocks, federal government of Nigeria bonds and interest rate. Using multivariate Vector Autoregression model, the results revealed that domestic debt plays an important role in the growth process of Nigerian economy judging from the high R 2 (0.983616) and the statistically significant Fvalue (102.0618) of the gross domestic product regression. The variance decomposition analysis revealed that federal government of Nigeria bonds exert more pressure on the growth rate of gross domestic product in Nigeria. The findings of the impulse response function in support of the variance decomposition analysis showed that economic growth responded positively to shocks in federal government of Nigeria bonds and negatively to shocks in treasury bonds throughout the ten year period. There is little or insufficient literature on the relationship between domestic borrowing on the Nigeria economy growth. In addition, the available studies on the subject matter have presented contradictory results and many closely related studies have typically focused on the relationship between poverty rate and economic growth of Nigeria. This study aims at filling this gap by using empirical econometric approach; since econometrics can be seen as the translation of economic theory and phenomena into feasible economic models subject to given assumptions and applying mathematical and statistical techniques for analysis, interpretation and inference. Using the most recent data from the period of 1981 to 2018 to investigate whether domestic borrowing benefit Nigeria's economic growth. The following are the objectives of this study; firstly, to examine whether the effect of domestic borrowing at current and some previous time points (lapse of time) have positive effect on Nigeria's real gross domestic growth (RGDP) a proxy for economic growth. Secondly, to examine whether there is long-run or short-run relationship between the two variables. Again, what is the nature of causality flow between domestic debt and economic growth in Nigeria using Granger causality? The remaining part of the paper is arranged as follows; section two presents the literature review, section three deals with materials and methods, section four presents data analysis and results and section five deals with summary and conclusion.
Materials and methods
The section provides information on method of data collection and sources, variable measurement and definition, model specification, method of estimation, method of unit root tests, co-integration approach and diagnostic test
Source of Data Collection
The data sets on real gross domestic product (RGDP) and domestic debt (DD) outstanding were obtained from published Central Bank of Nigeria (CBN, 2019) statistical bulletin as compiled by Debt Management Office and Central bank of Nigeria. The yearly time series data sets cover the period of 1981 to 2018.
Variable Measurement and definition
This paper uses real gross domestic product (RGDP) as the proxy for economic growth and domestic debt (DD) outstanding recorded in billions of naira. DD is represented by x and RGDP is represented by y respectively.
Model Specification
The model specification is to examine whether the effect of domestic borrowing at current and some previous time points have positive effect on Nigeria's real gross domestic growth (RGDP) a proxy for economic growth. Secondly, to determine if the ratio of domestic borrowing to RGDP has increased for the period under review, thirdly, to examine whether there is long-run or shortrun relationship between the two variables. Again, at what lapse of time can domestic debt effect economic growth in Nigeria.
Where, are regression parameters and is the stochastic error term. The et is the random error term which is assumed to independent and normally distributed with mean μ and variance ϭ 2 .
Lag Inclusion and Model selection
The lag inclusion in the regression model specified will be based on Schwarz criterion for model selection and diagnostic test of absence of serial correlation and heteroscedasticity in the selected model residuals.
Unit Root Test
The unit root test here, is based on Augmented Dickey Fuller (ADF) test and is of the form where k is the number of lag variables. In (2) there is intercept term, the drift term and the deterministic trend. The non deterministic trend term removes the trend term as seen in ( 3) And (4) removes both the constant and deterministic trend term in the above regression. ADF unit root test null hypothesis and alternative . According to Dickey, and Fuller (1979), if the ADF test statistic is greater than 1%, 5% and 10% critical values, the null hypothesis of a unit root test is accepted.
Co-integration Test
The co-integration framework developed by Johansen (1991, 1995) will be adopted in this paper and it is of the form;
where , , is a d-vector of deterministic variables, is a k-vector of integrated I(1) variables, is a vector of white noise with zero mean and finite variance. The number of co-integrating vector is represented by the rank of coefficient matrix . This method estimates the matrix in an unrestricted form and then test if one can reject the restriction imposed by the reduced rank of . The likelihood ratio test for the hypothesis that there are at most r co-integration vectors is known as the trace test statistic.
Vector error correction model (VECM)
If two time series are co-integrated the vector error correction model is a suitable modelling framework. The VECM for the case of DD and RGDP can be written as follows;
Where, rgdp=log (RGDP), dd=log (DD), ECT is the lagged error correction term derived from the long-run co-integrating relationship.
are adjustment parameter coefficients, is a difference operator and are random error terms assumed to be uncorrelated with mean zero. are the short-run or long term parameter.
Testing for the significant of parameter coefficients i.e, testing H0: for all i and H0: for all i in ( 6) and ( 7)
respectively will help in identifying the source of causation. Note that the significant of can be tested in ( 6) and (7). The significant of indicate how fast deviations from the long run equilibrium are eliminated by changes in each variable. The test can be accomplished via the F-test. If or , it indicate granger non-causality in the long run equilibrium or weak exogeneity. For the RGDP and DD, this means the both variables do not respond to a deviation from long-run relationship in the previous time period.
Data analysis and results
This section presents the data analysis and results of ADF unit root test, specified regression model, diagnostic tests of the estimated regression model, co-integration test, and Granger causality test are presented below; In order to check the order of integration of the variables under study, ADF unit root test is carried out and the result is presented in Table1 below;
| Variable | Deter-ministic Term | Lags | Test Value | 1% level 5%level 10%level | Prob. | Remark |
|---|---|---|---|---|---|---|
| DD | C,T | 8 | 1.924938 | -4.309824 -3.574244 -3.221728 | 1.0000 | I(1) |
| Log (DD) | C,T | 0 | -1.297387 | -4.226815 -3.536601 -3.200320 | 0.8730 | I(1) |
| Dlog (DD) | C,T | 0 | -4.652899 | -4.234972 -3.540328 -3.202445 | 0.0035 | I(0) under 10% level |
| RGDP | C,T | 0 | 4.472774 | -4.226815 -3.536601 -3.200320 | 1.0000 | I(1) |
| Log (RGDP) | C,T | 0 | -0.145063 | -4.226815 -3.536601 -3.200320 | 0.9920 | I(1) |
| Dlog (RGDP) | C,T | 0 | -3.288543 | -4.234972 -3.540328 -3.202445 | 0.0844 | I(0) under 10% level |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
The result of appropriate lag inclusion in model selection using SC and diagnostic test of absence of serial correlation and heteroscedasticity as shown in Table 2 above indicates that model 4 with lag integration of zero to three (0 -3) is more appropriate and preferred since it has the smallest value of SC. And the estimated model is presented below; The regression result in Table 3 can be represented below with the p-values in squared bracket as follows (8) The regression result in Table 3 indicates that domestic debt (DD) at lag1 and at lag2 exact positive effect on real gross domestic product (RGDP) significant at 5% level. The result also reveals that domestic debt has no direct effect on real GDP till after lapse of time say, 1 or 2 years interval. R 2 indicates that 37.2% variation in Nigeria's economic growth is accounted by Nigeria's domestic debt with a time lag of at three years. The F-statistic is significant showing the existence of linear relationship between economic growth and domestic debt outstanding in Nigeria. But Durbin-Watson statistic indicates presence of serial correlation in the residual. And since there is more than one lagged exogenious variable in the model, a further test of serial correlation will be done using Breusch-Godfrey Serial Correlation LM Test and the result is presented in Table 4 below; The test result in Table 5, Indicates the absence of heteroscedasticity in the model residuals since the probability values of the test statistics are not significant. The result of the test of normality in Figure 1 indicates that we accept the hypothesis of normal distribution of the model error term at the 1%,5% and 10% levels. Hence, we conclude that the model 4 specification is adequate.
| F-statistic | 0.852320 | Prob. F (4,29) | 0.5039 |
|---|---|---|---|
| Obs*R-squared | 3.576615 | Prob. Chi-Square (4) | 0.4663 |
| Scaled explained SS | 1.756566 | Prob. Chi-Square (4) | 0.7804 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
| Dependent variable: DLOG(RGDP) | — | — | — | — |
|---|---|---|---|---|
| Method: Least Squares | ||||
| Sample (adjusted): 1985 2018 | ||||
| Included observations: 34 after adjustments | ||||
| Variable | Coefficient | Std. Error | t-Statistic | Prob. |
| C | 0.078686 | 0.036138 | 2.177397 | 0.0377 |
| DLOG(DD) | 0.050719 | 0.107917 | 0.469984 | 0.6419 |
| DLOG(DD(-1)) | 0.282495 | 0.111859 | 2.525457 | 0.0173 |
| DLOG(DD(-2)) | 0.239704 | 0.108752 | 2.204130 | 0.0356 |
| DLOG(DD(-3)) | 0.038389 | 0.106432 | 0.360691 | 0.7209 |
| R-squared | 0.372086 | Mean dependent var | 0.194703 | |
| Adjusted R-squared | 0.285477 | S.D. dependent var | 0.103879 | |
| S.E. of regression | 0.087809 | Akaike info criterion | -1.892261 | |
| Sum squared resid | 0.223600 | Schwarz criterion | -1.667797 | |
| Log likelihood | 37.16844 | Hannan-Quinn criter. | -1.815712 | |
| F-statistic | 4.296164 | Durbin-Watson stat | 1.258429 | |
| Prob(F-statistic) | 0.007506 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
| Model | Predictor (xt-i) Lag length | AIC | SC | BG SC test p-value | BG H test p-value | Remark |
|---|---|---|---|---|---|---|
| 1 | 0 - 6 | -1.9366 | -1.5665 | F-val. 0.0921 R-sq. 0.0344 | F-val 0.8725 R-sq. 0.8249 | Serial corr. exist |
| 2 | 0 – 5 | -1.9452 | -1.6245 | F-val. 0.0871 R-sq. 0.0411 | F-val 0.9055 R-sq. 0.8736 | Serial corr. Exist |
| 3 | 0 - 4 | -1.8567 | -1.5846 | F-val. 0.3396 R-sq. 0.2245 | F-val 0.6852 R-sq. 0.6382 | No serial corr. |
| 4 | 0 - 3 | -1.8923 | -1.6678 | F-val. 0.2395 R-sq. 0.1719 | F-val 0.5039 R-sq. 0.4663 | No serial corr. |
| 5 | 0 - 2 | -1.7861 | -1.6083 | F-val. 0.0586 R-sq. 0.0446 | F-val 0.1732 R-sq. 0.1631 | serial corr. Exist |
| 6 | 0 - 1 | -1.6526 | -1.5206 | F-val. 0.0119 R-sq. 0.0105 | F-val 0.0613 R-sq. 0.0607 | serial corr. Exist |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
Analysis of Johansen cointegration test
The result of the examination of long-run relationship between domestic debt and economic growth result is shown in Table 6 below; The result of cointegration test in Table 6 reveals that the trace statistic (54.86043) is greater than 5% critical value (25.87211) indicating one (1) cointegrating equation at the 5% level. This implies that there is cointegration between domestic debt (dd) and real gross domestic debt (rgdp), thus, signifying that there is long run relationship between the two variables under investigation.
VEC model analysis
The estimation vector error correction model as specified in equation 6 and equation 7 is presented in Table 7 shows the result of VEC model. The result indicates the existence of short-run relationship between RGDP and DD in Nigeria at lag 1 as t -values are significant at 5% level, positive for DD and negative for RGDP. However, the coefficient of ECT in Equation ( 6) has a t-statistic of 5.22346 and it is significant at 5% level indicating long-run Granger causality exist from DD to RGDP, while the reverse does not. And at short-run, changes in DD exact positive effect on RGDP and it is significant under 5% level. It is also clear from the empirical result that RGDP at lag1 exacts negative effect on DD significant under 5% level.
| Vector Error Correction Estimates | — | — |
|---|---|---|
| Date: 01/22/20 Time: 18:34 | ||
| Sample (adjusted): 1984 2018 | ||
| Included observations: 35 after adjustments | ||
| Standard errors in ( ) & t-statistics in [ ] | ||
| Cointegrating Eq: | CointEq1 | |
| RGDP(-1) | 1.000000 | |
| DD(-1) | -7.889642 | |
| (0.43644) | ||
| [-18.0772] | ||
| C | -7102.111 | |
| Error Correction: | D(RGDP) | D(DD) |
| CointEq1 | -0.105847 | 0.081130 |
| (0.09898) | (0.01553) | |
| [-1.06940] | [ 5.22346] | |
| D(RGDP(-1)) | 0.566639 | -0.149690 |
| (0.22308) | (0.03501) | |
| [ 2.54007] | [-4.27611] | |
| D(RGDP(-2)) | 0.505975 | -0.045513 |
| (0.26215) | (0.04114) | |
| [ 1.93007] | [-1.10637] | |
| D(DD(-1)) | 3.310863 | 0.728956 |
| (0.80327) | (0.12605) | |
| [ 4.12171] | [ 5.78301] | |
| D(DD(-2)) | -1.000626 | 0.044828 |
| (1.26137) | (0.19794) | |
| [-0.79328] | [ 0.22648] | |
| C | -531.4976 | 705.7597 |
| (897.839) | (140.891) | |
| [-0.59197] | [ 5.00927] | |
| R-squared | 0.905283 | 0.864804 |
| Adj. R-squared | 0.888953 | 0.841495 |
| Sum sq. resids | 52188366 | 1285115. |
| S.E. equation | 1341.491 | 210.5096 |
| F-statistic | 55.43517 | 37.10079 |
| Log likelihood | -298.4257 | -233.6055 |
| Akaike AIC | 17.39576 | 13.69174 |
| Schwarz SC | 17.66239 | 13.95838 |
| Mean dependent | 3645.701 | 364.3480 |
| S.D. dependent | 4025.630 | 528.7497 |
| Determinant resid covariance (dof adj.) | 7.97E+10 | |
| Determinant resid covariance | 5.47E+10 | |
| Log likelihood | -532.0275 | |
| Akaike information criterion | 31.20157 | |
| Schwarz criterion | 31.82371 | |
| Number of coefficients | 14 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
Pairwise granger causality tests
In order to examine whether domestic borrowing granger causes economic growth in Nigeria, the pairwise Granger causality test is carried out as presented in Table8 below; The result of Granger causality tests as presented in Table 8 above reveals that domestic debt (DD) granger causes economic growth (measured via RGDP) up to the 7 th lag as the p-values are all significant under 5% level. This result implies the existence of unidirectional Granger causality flow from DD to RGDP in Nigeria.
| Sample: 1981 2018 | — | — | — |
|---|---|---|---|
| Lags: 1 | |||
| Null Hypothesis: | Obs | F-Statistic | Prob. |
| DLOG(RGDP) does not Granger Cause DLOG(DD) | 36 | 0.00227 | 0.9623 |
| DLOG(DD) does not Granger Cause DLOG(RGDP) | 5.37989 | 0.0267 | |
| Lags: 2 | |||
| Null Hypothesis: | Obs | F-Statistic | Prob. |
| DLOG(RGDP) does not Granger Cause DLOG(DD) | 35 | 0.05514 | 0.9464 |
Table text extracted from the original PDF; superscript letters are shown inline. The original table image is below.
View original table image
Discussion of results
The result lagged exogenous regression model as presented in Table3 indicates that domestic debt at lag1 and lag2 have positive effect on RGDP significant under 5% level. This implies that domestic debt enhances economic growth after one or two lapses of time (say, 1 or 2 years). Hence, result indicates generally that RGDP benefits positively from DD in Nigeria. This finding is in line with that of Peter et al. (2013), Onogbosele and Mordecai (2016) all for Nigeria and Muhammad et al. (2010) [11] for Pakistan who found domestic debt positively affecting economic growth. The finding contradicts that of Adoufu and Abula (2010) [1] who showed that domestic debt has negatively affected the growth of Nigerian economy. Adoufu and Abula finding could be attributed to lack adequate yearly data (covering only 1986-2005)
The empirical result also showed that domestic debt and economic growth are cointegrated. This finding is not in agreement with that of Singh (1999) for India. The results from the VEC model showed that both long-run and short run relationship exist between RGDP and DD but the Granger causality flow only in one direction (from DD to RGDP). The result also showed that domestic debt (DD) granger causes economic growth (measured via RGDP) up to the 7 th lag as the p-values are all significant under 5% level.
Conclusion
The finding of the study revealed that domestic debt have significant positive effect on economic growth after some lapse of time (1 to 2 years) both in the short-run and long-run. Thus, it becomes imperative for government to consider domestic window for borrowing than external window as this has proven to be beneficial to Nigeria's economic growth.
References
16 in the original paper- Adofu I, Abula M. Domestic Debt and the Nigerian Economy. Current Research Journal of Economic Theory. 2010; 2(1):2226.
- Abbas Ali, Jakob Christensen. The Role of Domestic Debt Markets in Economic Growth: An Empirical Investigation for Low-income Countries and Emerging Markets. IMF WP. 2007; 07:127.
- Barro, Robert J. Are Government Bonds Net Wealth. Journal of Political Economy. 1974; 82:1095-1117.
- Damian KU, Chukwunonso SE. Domestic debt and private investment in Nigeria. Int J of Sci Res and Edu. 2014; 8(2):23217545.
- Dickey DA, Fuller WA. Distribution of the Estimators for Autoregressive Time Series with a unit root, Journal of the American Statistical Association. 1979; 74:427-431.
- Fry M. Emancipating The Banking System and Developing Markets for Government Debt. (London: Routledge), 1997.
- Johansen, Søren. Estimation and Hypothesis Testing of Cointegration Vectors in Gaussian Vector Autoregressive Models, Econometrica. 1991; 59:1551-1580.
- Johansen, Søren. Likelihood-based Inference in Cointegrated Vector Autoregressive Models, Oxford: Oxford University Press, 1995.
- Kemal AR. Debt Accumulation and Its Implications for Growth and Poverty. The Pakistan Development Review. 2001; 40(4):263-281.
- Maana Isaya, et al. Domestic Debt and its Impact on the economy -The case of Kenya paper presented during the 13th Annual African Econometric Society Conference in Pretoria, South Africa, 2008.
- Muhammad RS, Muhammad ZF, Khadija T. Studied the relationship between domestic debt and economic growth in Pakistan: An Empirical Analysis. Pakistan Journal of Social Sciences (PJSS). 2010; 30(2):373-387.
- Onogbosele DO, Mordecai DB. The Impact of Domestic Debt on Economic Growth of Nigeria. Asian Research Journal of Arts & Social Sciences. 2010; 1(3):1-13.
- Schclarek A. Debt and Economic Growth in Developing Industrial Countries, mimeo. available on-line, 2004. http://www.nek.lu.se/publications/workpap/Papers/WP05_34.pdf
- Singh, charan. Domestic Debt and Economic Growth in India. Economic and Political Weekly. 1999; 34(23):1445-1453.
- Tamunonimim AN. 2013. Domestic debt and poverty in Nigeria: An empirical time series investigation. Euro J of Acct Aud and Fin Res. 1999; 5(2):33-47.
- Uzochwkwus, Amakom. Nigeria Public Debt and Economic Growth: Anempirical Assessment of Effects on Poverty. African Institute for Applied Economics Enugu Nigeria, 2003.